Quite often, the parties form a flawed idea of the price. Some buyers believe they can land a bargain by acquiring a hidden gem for next to nothing. Nowadays, on the pretext that transaction prices have fallen dramatically, they are inclined to make lowball, or even insulting, offers. On the other hand, some sellers hold an inflated view of their company's value. Flattered by unrealistic valuations and encouraged by advisers with a vested interest in the status quo, they make excessive demands. The legend of the wealthy patriarch—eager to buy a business at any cost for his spoiled son—dies hard! In another scenario, the seller sets their price solely based on their personal retirement goals, completely disregarding the company's financial realities.
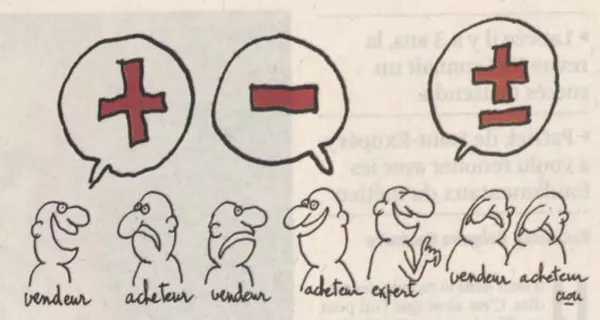
In reality, while it is true that certain purely subjective factors can play a role in price negotiations, such situations are rather exceptional. A buyer may fall in love with the company, be convinced of its huge growth potential, or simply offer an excessive price due to the pressure of competing offers. Conversely, a seller might let their business go cheaply due to their health condition or personal affinity for the buyer. Generally, however, each party wants to obtain the price that seems fair to them.
What then is the "fair price"? And how do you bridge the gap when viewpoints seem diametrically opposed? The key to success in price negotiations lies in moving from desires to reality, from the subjective to the objective. Anyone who wants an agreement must be capable of listening to reasonable arguments. This is where the concept of valuation comes into play. It is often said: "Valuation is not the price." However, one should add that: "Valuation is often the starting point of the price." The better prepared the valuation, the higher the chances of achieving the fair price. Various valuation methods make it possible to establish an argued price range. Depending on the scenario, it is advisable to cross-reference different valuation methods and take a weighted average, with the weighting itself also subject to discussion.
To avoid going off course, it is important that price negotiations are guided by business transfer professionals who can—while defending their client's interests—bring viewpoints closer together by comparing their valuations. If these have been conducted thoroughly, they should not differ too greatly from one another.
The buyer must agree to pay a fair price reflecting the real value of the assets owned by the company, as well as a goodwill justified by the business's profitability. It is therefore necessary to account for capital gains adjusted for deferred tax liabilities. Goodwill encompasses all intangible assets (brand, reputation, customer base, leasehold rights) and is valued relative to recurring profitability. Thus, a loss-making business has no goodwill.
There are numerous valuation methods, but the most common method consists of applying an EBITDA multiple (operating profit + depreciation and amortization) adjusted for net debt (financial debt and inter-company debt, minus cash and available securities). In the SME segment, a multiple of 4 or 5 is generally used. To get a rough idea of an SME's value, one can therefore use the following method, which is very simple to apply: 4 or 5 x EBITDA +/- Net Debt or Net Cash.
The seller must understand that the acquisition price paid by the buyer must be repayable within a reasonable timeframe. Most acquisitions are bank-financed, and lenders will require sufficient debt service capacity from the company over a 7-year period (the maximum term for an acquisition loan). The buyer's equity contribution generally required is around 25-30%. These parameters allow for a simple yet effective check to see if the requested asking price holds water.
The fair price is therefore the equilibrium point reached if each party can listen to the other's reasonable arguments.
Illustration: Clou
