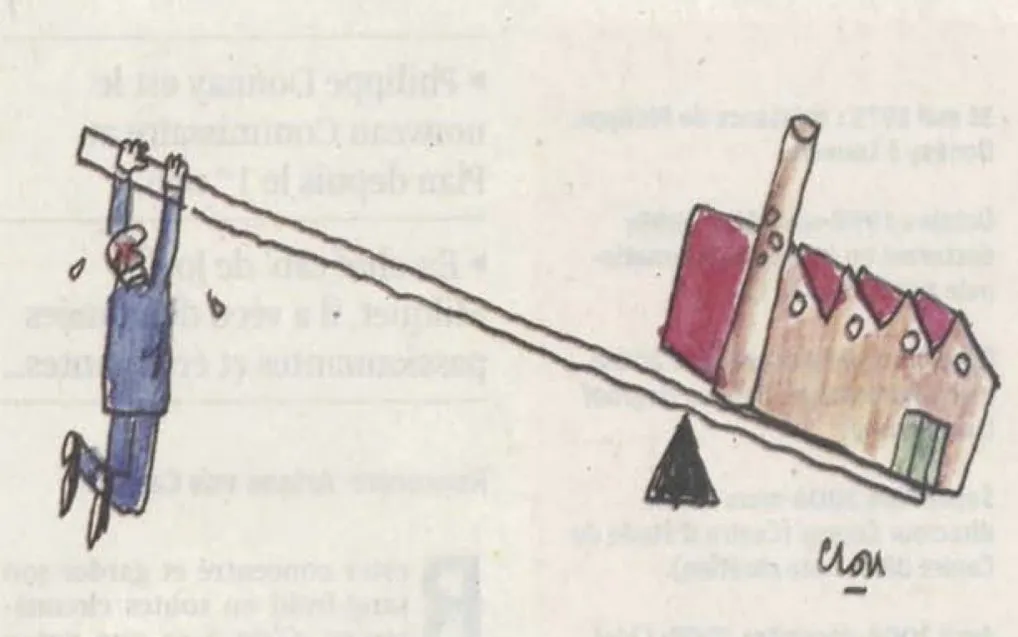
How does this financial leverage work?
In financial jargon, the leverage effect is an accounting concept that measures the impact of financial debt relative to the company's equity. When a company's return on investment is higher than the prevailing market interest rate, the investor stands to benefit from using debt. By committing a limited amount of equity, they can capture the spread between the company's economic return and the loan's interest rate, thereby boosting their return on equity (ROE).
In this period of low interest rates, leverage can be particularly attractive. However, financial leverage sometimes suffers from a bad reputation. Leveraged Buy-Outs (LBOs), when executed too aggressively, can lead to disaster. If economic conditions turn and the company's cash flow is no longer sufficient to service its debt obligations, catastrophe lies ahead. In a sense, this leverage ratio is the inverse of the solvency ratio, which measures a company's financial stability. The higher the equity, the more solid the company—but the lower its return on equity will be.
In what proportion should financial leverage be used?
In the context of a business acquisition, the return on investment must be calculated over a short time horizon, as the perceived risk is fairly high. Company valuation can be measured as a multiple of profitability (for example, a multiple of EBITDA, gross cash flow, or net profit). These multiples vary depending on the sector, market conditions, or negotiation dynamics. In practice, the transaction price often hinges on the limits of bank financing.
Indeed, banks typically only lend over a 7-year term while requiring an equity contribution of at least roughly 30%. Furthermore, the business plan is subjected to stress testing (a worst-case scenario), meaning available cash flow cannot be fully earmarked for debt repayment. Consequently, most acquisition debt is amortized within 5 to 7 years. In other words, if an investor contributes 33% in equity, the value of their equity stake in the company will have tripled by the time the bank loan is fully repaid, purely through the effect of financial leverage.
What other levers can be combined with financial leverage?
If, in addition, the company's profitability increases—what some refer to as operational leverage—the benefits become even more substantial. An increase in cash flow will have an exponentially greater impact on the return on investment when combined with high financial debt. These two leverage effects do not merely add up; they multiply, as one sits in the numerator and the other in the denominator of the same financial equation.
Similarly, if the acquired company takes on new debt to invest in productive projects, the return is multiplied further. A cascade of holding companies, each utilizing debt, makes it possible to minimize equity while securing the necessary funding for projects. Bringing in third-party investors (private equity) can also be viewed as a form of leverage. Tax systems somewhat encourage this operational structure, as interest expenses are tax-deductible—a phenomenon known as tax leverage.
The deductibility of interest expenses also applies when the acquisition loan is structured through a holding company. It is worth noting, however, that in Belgium, the nominal interest deduction (notional interest deduction) was introduced to counterbalance this advantage by granting a tax deduction capped at a theoretical yield on equity.
Thus, a business leader's ability to develop projects that yield more than the risk-free interest rate, while maintaining a reasonable level of debt, is exceptionally well rewarded. Every risk, however, must be measured, as one must remain capable of handling unforeseen events to avoid bitter disappointments.
Illustration: Clou
